
Your Amazon U.S. customs duty calculation changed as of July 24, 2026. Products from a number of origin countries became subject to an additional duty under Section 301, at 12.5 percent for countries in the upper tier. The decision was announced by USTR on the evening of July 23, 2026. Categories where many international sellers are active, such as food, cosmetics, dietary supplements and home textiles, are not on the general exclusion list for this duty.
The 15 percent rate still mentioned in the market no longer applies. That layer was removed entirely in February 2026 following a Supreme Court decision. Today the country-specific additional layer in effect is the Section 301 duty, at 12.5 percent in the upper tier.
In this article we explain how the new rate enters your FBA cost sheet, which products are covered, which sales model is actually affected by the end of the de minimis exemption, and the textile quota expected to be clarified on September 1.
What exactly is Amazon U.S. customs duty?
Amazon U.S. customs duty is the total of the duties paid when your product clears U.S. customs. Amazon does not collect this duty; the importer of record pays it. For FBA shipments, that is usually you or your importer in the U.S.
The total burden is not a single rate. Additional layers based on country and policy are added on top of the base duty (MFN) tied to the product's HTS code. From July 24, 2026, one of these layers for products from the affected countries became the Section 301 forced labor duty.
The decision was made through the Office of the U.S. Trade Representative's final action dated July 23, 2026, and published in the Federal Register on July 28, 2026 (document number 2026-15181). The implementation instructions on the customs side are in CBP's CSMS message number 69326983.
Why is the 15 percent figure no longer correct?
The 15 percent rate many exporters remember was the reciprocal tariff layer imposed under IEEPA authority. On February 20, 2026, the Supreme Court ruled that IEEPA does not give the president the authority to impose additional customs duties. An executive order issued the same day (EO 14389) removed all additional duties based on that authority.
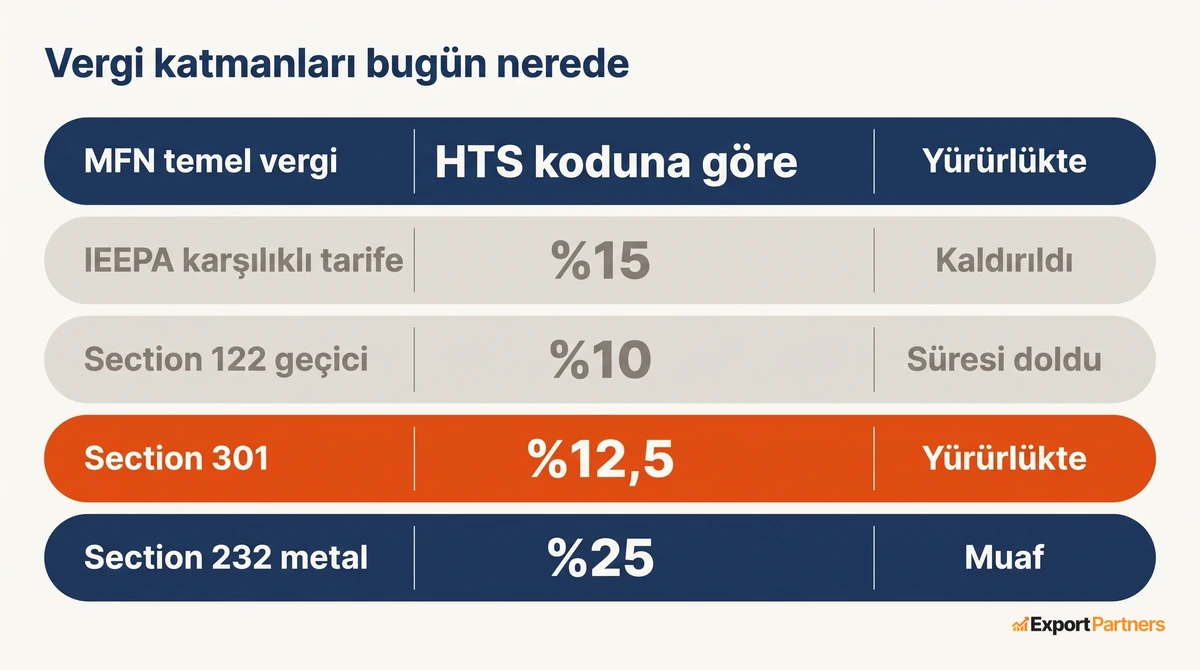
It was replaced by a temporary 10 percent import surcharge under Section 122 of the Trade Act. The legal duration of this measure is 150 days, which runs to July 24, 2026. The text states that the period can be extended only by an act of Congress. No extension has been published, but there is also no separate announcement confirming that it has ended.
The practical result: the 12.5 percent under Section 301 is certain and in effect. Whether another general layer is added on top of it should be confirmed with your customs broker based on your shipment date. The most common mistake is adding the 12.5 percent on top of the 15 percent that some still believe exists. That total does not exist.
| Layer | Rate | Status |
|---|---|---|
| MFN (base duty) | Varies by HTS code | In effect |
| IEEPA reciprocal tariff | %15 | Removed on February 20, 2026 |
| Section 122 temporary surcharge | %10 | 150-day period ended on July 24, 2026; current status should be confirmed |
| Section 301 forced labor | %12,5 | Started on July 24, 2026, in effect |
| Section 232 metal derivatives | 25% base | In effect, exempt from 301 |
Why was this duty introduced?
The Section 301 investigation targets a gap in the legislation of the countries concerned: the absence of a rule banning imports of goods made with forced labor. The decision is not based on a claim that forced labor exists in those countries' production.
This distinction can matter in your customer communication. A U.S. buyer who misreads the news may conclude that goods from your country have been classified as forced labor products. Explaining the actual basis correctly is a step that helps protect your business relationship.
The action covers 60 economies. Of these, 17 are in the 10 percent tier because they committed to the relevant import ban. The others are currently in the upper tier at 12.5 percent. In theory, a country's rate could drop if it makes that commitment, but this depends on each government's own decisions.
Which products are covered, and which are exempt?
CBP's published general exemptions form a short list: civil aircraft products, pharmaceuticals, metals and derivatives covered by Section 232, humanitarian donations, and informational materials. Food, cosmetics, dietary supplements, and home textiles are not on this list.
The annexes to the decision (Annex I and Annex II Part A) also include product-specific exceptions. These annexes use criteria such as "products that cannot be produced in sufficient quantity in the U.S." and are made up of line-by-line HTS code lists.
The practical takeaway: if your category is not in the general exemptions, that does not mean your specific HTS code is covered. Checking your own code against the annex lists one by one is safer than guessing.
There is also a transition exception. Goods loaded before July 24, 2026 and entered into the U.S. before July 28 were exempted from this duty.
How does your landed cost calculation change?
The formula is simple: the MFN rate plus 12.5 percent, applied to the CIF value. On the entry summary, the Section 301 duty is reported under Chapter 99, ahead of Section 232.
If you use a Foreign-Trade Zone (FTZ), there is one point to watch: the goods need to enter with privileged foreign status. Section 301 duties do not apply to entries under Chapter 98.
The table below shows the standalone effect of the Section 301 duty on a CIF value of $10,000. The MFN rate is assumed at 4 percent as an example; the rate for your own code will differ.
| Item | Amount |
|---|---|
| CIF value | 10,000 USD |
| MFN (example 4%) | 400 USD |
| Section 301 (12.5%) | 1,250 USD |
| Total of these two items | 1,650 USD |
| Per unit (1,000-unit lot) | 1.65 USD |
In this example, the Section 301 duty alone adds $1.25 to the unit cost. Your product's own MFN rate comes on top of that, so the actual total depends on your code. Giving a single total figure would be misleading. This amount is paid up front when the goods enter the U.S., while sales revenue comes back weeks later. For the duty's effect on your cash cycle, see our article on Amazon FBA cash flow and the payment cycle.
Which sales model does the de minimis change affect?
The $800 de minimis exemption has been suspended for all countries since August 29, 2025. Two CBP rules published on June 24, 2026 made the suspension indefinite and moved its legal basis from an executive order to a statutory provision. On July 1, 2027, the exemption will be removed from the statute entirely.
There is no country-specific exception. The suspension applies to all countries alike.
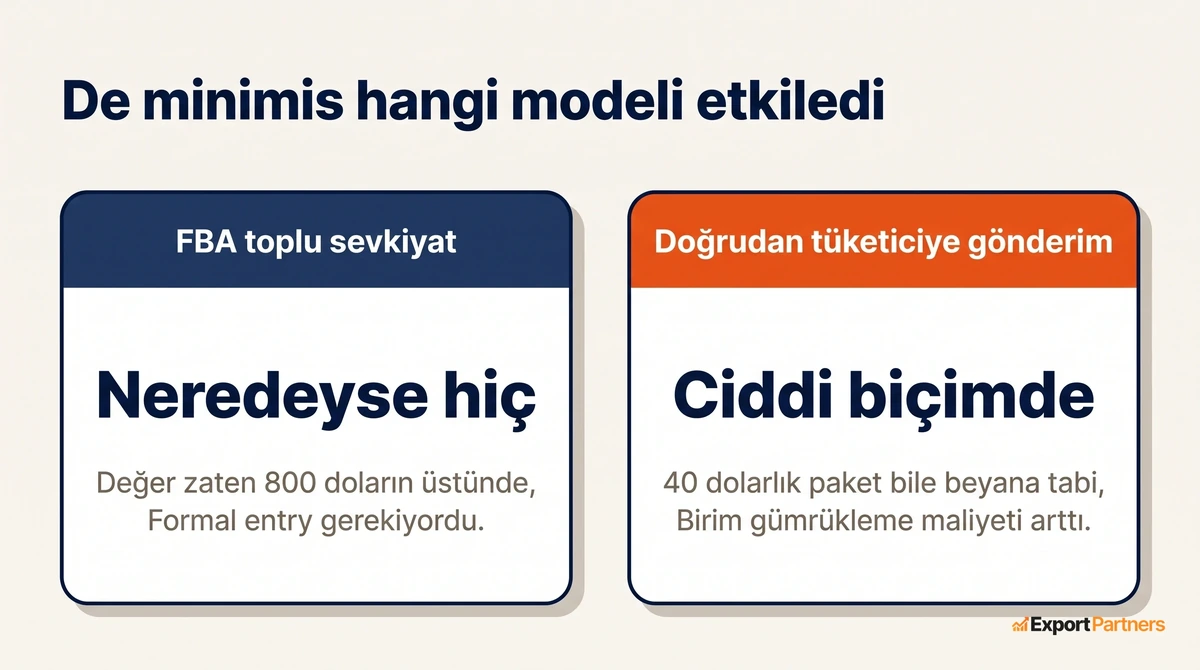
The key point is this: the change affects two sales models very differently, and many sellers are worried about the wrong side.
| Model | Affected? | Why |
|---|---|---|
| FBA bulk shipment | Hardly at all | The value was already well above $800 and required a formal entry. De minimis never applied to this model |
| Direct-to-consumer shipping | Significantly | Even a $40 package is now subject to declaration and duty. Per-unit clearance costs and delivery times have increased |
So if you work with the FBA model, the de minimis suspension has had no direct effect on your cost structure. If you ship orders one by one from your own website, Etsy, or via FBM, the impact can be significant.
There is also a common misconception: it is often said that goods covered by Section 301 and 232 could never use de minimis anyway. That is not correct. Before the suspension, these goods could also benefit from the exemption, and CBP noted in its own proposed rule that a large share of low-value shipments avoided additional duties this way.
Entry Type 86 has also been eliminated. Entries of $2,500 and under are now filed as informal entries through ACE.
What should you do with your FBA pricing?
A rushed price increase is not always the right move. On Amazon, a price change affects sales velocity, and velocity affects organic ranking. Putting your ranking at risk over a two-and-a-half-point cost increase may be disproportionate.
A more sensible sequence could be this: first, determine which duty regime your current inventory entered under. Stock that entered before July 24 still carries the old cost. Changing the price while waiting for the next shipment can unnecessarily raise or lower the margin on the goods you already hold.
The second step is to look at the cost per conversion in your PPC budget. A two-and-a-half-point improvement on the advertising side can often offset the increase on the customs side.
If you want to review the full cost structure of your Amazon operation, we build this calculation together with you as part of our Amazon service.
Textile quota to be clarified on September 1
A Presidential Memorandum published on July 28, 2026 directs the Office of the U.S. Trade Representative to establish a tariff-rate quota on certain textile and apparel imports and to assess its feasibility by September 1, 2026.
The scope of this quota has not yet been announced. It is unclear whether it will include home textiles (Chapter 63 items such as towels, bathrobes, and bed linens). If you sell in these categories, this is the nearest development to follow.
Two commonly confused topics
The first is UFLPA. It is not a duty but an import ban with a rebuttable presumption mechanism. All companies added to the list in the August 2026 update are located in China.
The second is WRO and Finding decisions. These target specific producers and regions, and CBP publishes the active list. Checking it against your own country and suppliers is worthwhile.
What should you do now?
We suggest three steps, in order. First, check your own HTS code against the decision's annexes. Next, separate your inventory by the date it entered. Finally, rebuild your pricing.
If you have shipments that entered the U.S. between February and July 2026, refund processes related to the expired tiers may be relevant. This directly concerns your U.S. importer, so it is worth discussing with them.
For customs classification and entry filing, see our U.S. and Canada customs service. If your product is a food or cosmetic, the registration steps in our article on selling cosmetics on Amazon in the U.S. and MoCRA compliance should be completed before you calculate duties. If registration is incomplete, a product may be stopped at entry before duty even comes into play; we explain how that process works in our FDA import refusal guide.
Frequently asked questions
Does Amazon collect this duty from me?
No. Customs duty is paid to U.S. Customs by the importer of record. For FBA shipments, that is usually you or your importer in the U.S. The charges Amazon collects are referral fees and FBA fees, which are separate.
Does the 12.5 percent rate apply to every product?
The 12.5 percent rate applies to goods from the economies in that tier. However, the annexes to the Federal Register notice dated July 28, 2026 list product-specific exclusions, and metal products covered by Section 232 are exempt from this duty. Exempt lines are grouped under heading 9903.05.87 in the tariff schedule and can be tracked through the list published by CBP. You will need to check your own HTS code.
Does this duty apply to my existing stock?
Goods loaded before July 24, 2026 and entered into the U.S. before July 28 were exempted. Stock already sitting in a U.S. warehouse was taxed under the rules in effect on the date it entered.
Is this rate permanent?
Under Section 301, the rate depends on whether the country concerned commits to banning imports of goods made with forced labor. The 17 economies that made this commitment are in the 10 percent tier. If no such commitment has been announced for your country, planning around the 12.5 percent rate is the more cautious approach.
Will the $800 exemption come back?
The suspension has no end date, and it can only be lifted if CBP announces it in the Federal Register. In addition, the exemption will be removed from the statute on July 1, 2027. After that date it cannot be restored by an administrative decision; a new law would be required. It is safer to plan on the assumption that this change is permanent.
Are these goods banned in the U.S.?
No. This is an additional duty, not an import ban. It is still worth checking CBP's active WRO and Findings list and the UFLPA Entity List for your country of origin and your suppliers.
Conclusion
The change in U.S. customs duty for Amazon sellers is not as sharp as the headlines suggest. The effective increase is two and a half points, which most private label products can likely absorb.
The real risk is planning with the wrong number. A cost sheet built on 15 percent no longer reflects reality. Verifying your own HTS code, separating your stock entries by date and following the September 1 textile quota decision are the three concrete steps for the period ahead.
The rates and dates in this article were compiled from the Federal Register, the Office of the U.S. Trade Representative and CBP. Trade policy rules change often, so we recommend confirming the current status before making decisions about your own shipment.
Last updated: August 30, 2026

